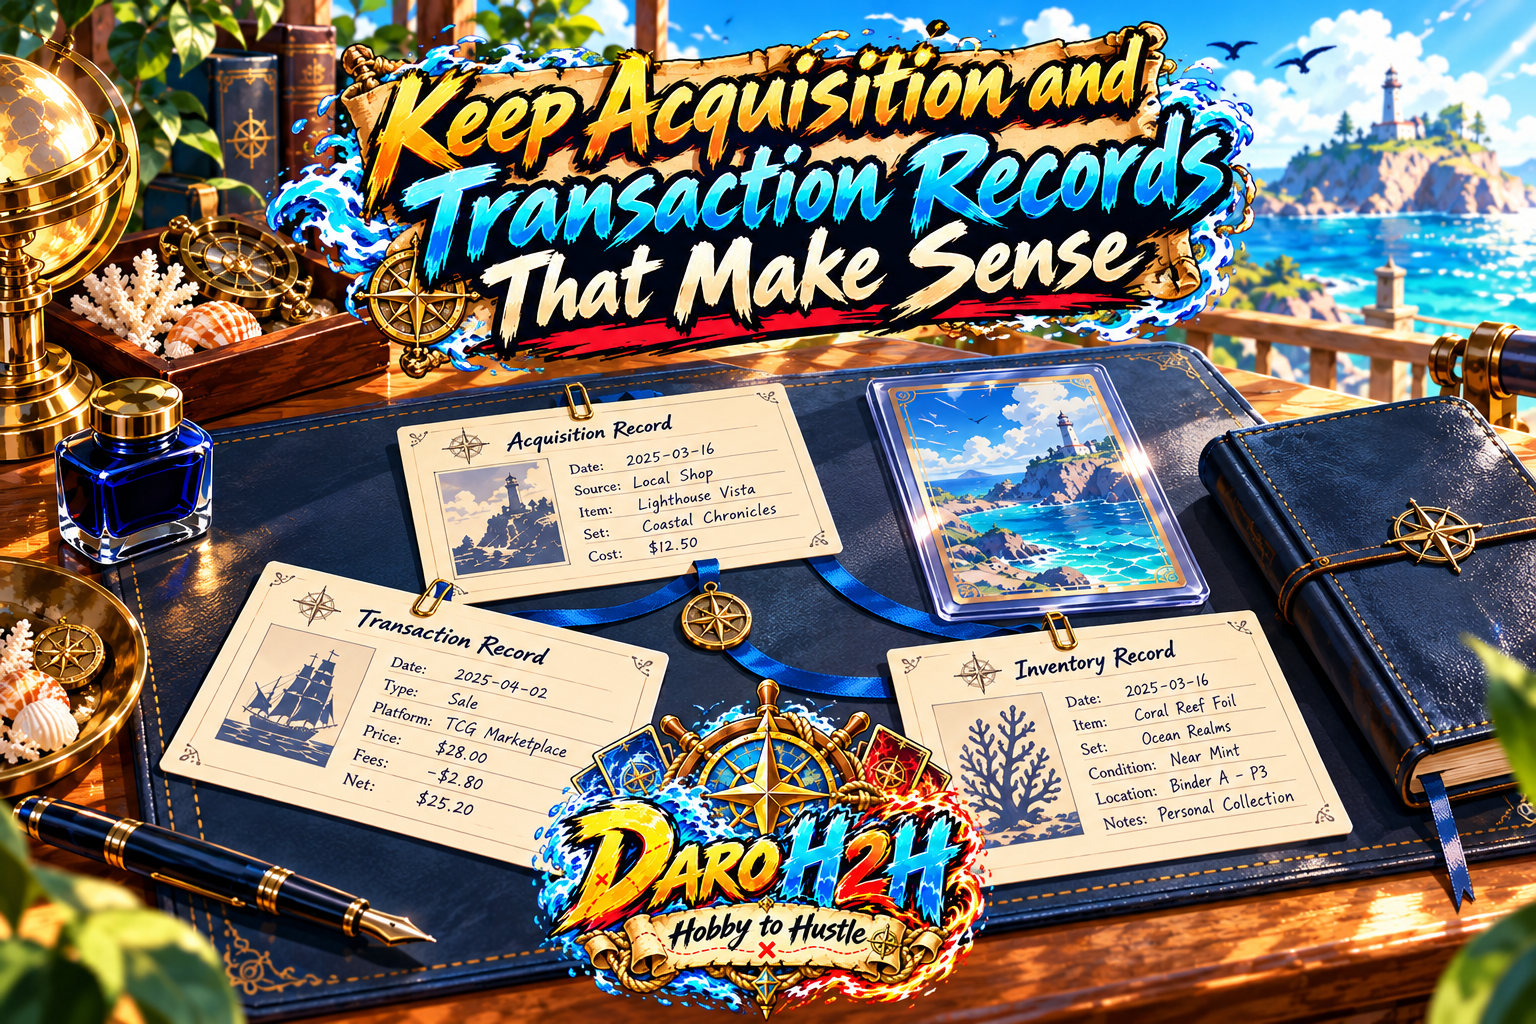
It’s easy to remember the exciting part of a pickup: the artwork, the trade, the moment a missing binder slot finally filled. The less exciting details tend to disappear. Was shipping included in that amount? Did the card come from a larger lot? Was that number what you paid, what you hoped to sell for or what somebody offered last month?
Useful collection records keep those answers separate. You don’t need to turn every card into a business asset. You do want enough history to understand what you own, what changed hands and where the money numbers came from.
Start with the information you actually have. An honest unknown is better than a tidy-looking guess that becomes harder to recognize later.
Connect the card to the transaction
Give a card or lot an identifier you can use consistently in your own records. Then record enough identity detail to distinguish it from similar copies: game, set or product, card number, language, variant and quantity. Add raw-condition notes or grading-company and label details when relevant.
For an acquisition, record the date, how it arrived, the currency, the known amount and a source reference. A purchase, trade, gift and inheritance are different kinds of history. Don’t squeeze all four into a “purchase price” field just because the spreadsheet offers one.
The source reference can point to a receipt, order confirmation, payment record or written trade agreement. You don’t have to repeat every detail in every place. The useful connection is being able to move from a card record to the evidence that explains it.
If the card later leaves the collection, preserve that history rather than deleting the row. Record whether you sold, traded, gifted or otherwise disposed of it, along with the relevant date and transaction reference. A collection ledger can tell a story over time without making departed cards look like current inventory.
Say what each amount includes
“Paid $40” is a good start, but it leaves a question: $40 for the card alone, or $40 after shipping and tax? Record the scope while the receipt is in front of you. Currency matters too, especially when your records include purchases in more than one country.
You can store the components separately or record a total with a clear inclusion note. Either way, avoid silently mixing all-in totals with item-only amounts when comparing purchases. The arithmetic can be correct while the labels make the comparison misleading.
If an exchange includes cash and cards, record both sides. A $10 cash adjustment doesn’t mean the card you received “cost $10” in every useful sense. It tells you that $10 moved alongside a noncash exchange. Keep the exchanged items visible so the record doesn’t erase most of the transaction.
For personal records, describe estimates and allocations as estimates and allocations. Don’t call them tax basis unless a qualified professional has established that treatment for your facts. A hobby ledger is a place to preserve information, not a machine for deciding tax law.
Unknown is different from zero
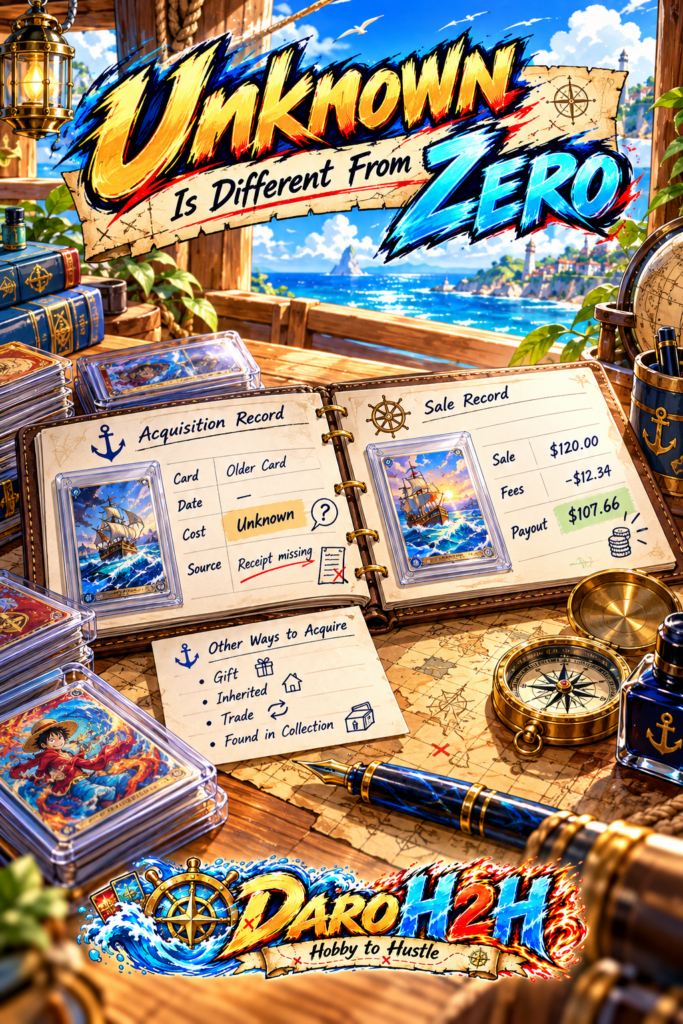
An old card without a receipt may have an unknown acquisition amount. Entering zero makes it look as though you know there was no recorded cost. Those are different statements, and they can produce very different results if a calculator later subtracts the field from sale proceeds.
Use a blank or explicit unknown status according to the tool’s design, with a note about what is missing. If you have a rough memory, keep it as an unverified estimate rather than promoting it to a confirmed amount. Add the source and date if you later recover an order record.
Gifts and inherited cards need particular care. A lack of cash paid by you doesn’t settle every recordkeeping or tax-basis question. Record how the item came to you, the information you have and what you still need to ask. Don’t invent a purchase price to make the row feel complete.
You can still keep useful current records while earlier history is incomplete. Today’s sale amount, fees and payout can be known even when the original acquisition details are not. Let the system show which result is available and which is not.
Keep a lot’s original total intact
Suppose, in a hypothetical example, you buy a small lot for $50 and later decide to keep two cards and sell three. The original $50 transaction should remain visible even if you create individual records for the five cards.
If you allocate that amount for personal tracking, label the method and make sure the assigned amounts reconcile to the original total. An equal split, a weighted split or another method answers different bookkeeping questions. None becomes an authoritative tax method simply because it was easy to calculate.
Keep the allocation separate from price estimates. A card getting more expensive later doesn’t change the amount you actually paid for the lot. And deciding one card is your favorite doesn’t automatically make the rest “free” for every recordkeeping purpose.
If the allocation affects a tax return or a material selling decision, ask a qualified professional how to handle the actual circumstances. Bring the original lot receipt and your proposed method rather than just the final spreadsheet figures.
Keep order, sale and payout records distinct
A completed sale can produce an item amount, buyer-paid shipping, fees, a label charge, a payout and later adjustments. Those are related records, but they aren’t interchangeable.
Store the order reference with the card or lot. Save the platform’s transaction and payout details so you can see which fees were withheld, which costs were paid separately and whether several sales were grouped into one payment. A bank deposit alone may not explain the underlying orders.
The IRS says to use Form 1099-K with other records when determining what to report. That is one reason to preserve the platform statements instead of treating a gross information-reporting total as your profit or bank deposits.
Record returns, refunds and fee adjustments against the original transaction. Don’t delete the sale and hope the remaining cash total tells the whole story. If a card comes back, note its return to the collection and any condition change that needs attention.
Save evidence where you can find it
Choose a naming approach that’s easy to keep using. An order reference plus a date is often enough to connect receipts and photos with the corresponding ledger entry. The best system is the one you can maintain after the excitement of a new organization project wears off.
Keep an accessible backup or export of important records. Check that you can actually open it and understand the columns. A file stored somewhere you cannot retrieve later isn’t doing much for future you.
Protect private information while keeping useful history. A collection ledger doesn’t need passwords, full payment-card details or a publicly visible copy of every buyer’s address. Use transaction references and store delivery information only where it is needed for the legitimate transaction and required records.
If you share a collection list with another collector, create a version suited to that purpose. They may need the card identity and availability, not what you paid or the private details of the person who sold it to you.
Make the routine small enough to keep
After a purchase, save the receipt and add the item or lot. After a trade, record what left and arrived. After a sale, connect the order, costs and eventual payout. You can do more detail for significant cards and simpler records for modest lots, provided the meaning of the fields stays clear.
An occasional check against your actual collection and statements helps catch duplicates, missing disposals and unexplained amounts. Fix the underlying record when you can; mark unresolved differences instead of forcing a total to balance.
The Portable Collection Ledger and Hobby Budget and Cashflow Log serve different jobs. The first preserves item history. The second follows money moving through the account or pocket you chose to track. Keeping those jobs separate makes both easier to use.
Quick questions
Should I enter zero if I don’t remember what I paid?
No. Mark the history unknown unless zero is genuinely the known amount for that field. A missing receipt isn’t evidence that the acquisition cost was zero.
Can I record a sale without knowing the original cost?
Yes. Record the known sale, fee and payout information. Leave any result requiring the acquisition amount unavailable until you have supported information.
Does dividing a lot price between cards establish tax basis?
Not automatically. It creates an allocation for the purpose you label. Ask a qualified professional about tax treatment and retain the original transaction evidence.
Start with your next transaction
Don’t wait until the entire old collection is reconstructed. Record the next purchase or trade clearly, save the supporting evidence and build from there. A small number of trustworthy entries is a much better foundation than hundreds of guesses.