A marketplace sends you a payout, you add it to the hobby log, then you subtract the fees shown on the order. That sounds careful. If the fees were already withheld before the payout, though, you’ve just counted them twice.
A cash-flow log becomes much easier to use when it follows one rule: record the money that actually enters or leaves the account or pocket you’re tracking. Keep the sale’s detailed economics in the transaction record. Keep unsold card estimates out of the cash total.
You can still connect all those records. They just don’t need to do the same job.
Choose what your log is following
Decide whether you’re tracking one account, a separate hobby cash balance or a defined set of accounts used for card activity. Write that scope down. Otherwise a transfer between your own accounts can look like new income in one place and a mysterious expense in another.
If the log follows a single account, a transfer into it changes that account’s balance, but it still isn’t a card sale. If you’re tracking several accounts together, movement between them doesn’t create new money for the combined group. Label transfers so the scope remains clear.
You don’t need a separate bank account to keep a personal hobby record. You do need a consistent way to recognize which movements belong in the view you’re building. If you are operating a business, get appropriate accounting advice rather than treating this lightweight hobby log as a complete business system.
Use the amount that actually arrived
A net marketplace payout is the amount that reached the tracked account after the platform’s deductions or adjustments. Record that actual inflow, with its date and payout reference. Keep the related order details available so you can explain what the payout contains.
For a fictional example, suppose an order’s sale-related receipts total $50 and the platform withholds $7 in fees and a $5 shipping label. A $38 payout reaches your account. In a cash log following that account, the inflow is $38. Recording $38 and then another $12 of outflows for those same withheld charges would understate the cash movement.
That doesn’t erase the fees from your records. They belong in the transaction breakdown that explains the payout. You are simply avoiding the claim that the same money left your account twice.
A payout may combine several sales or include refunds, credits and other adjustments. Reconcile it to the statement before assuming it represents one card. If part of it is unexplained, mark the record for review rather than assigning the difference to a random sale.
Record separate payments when they happen
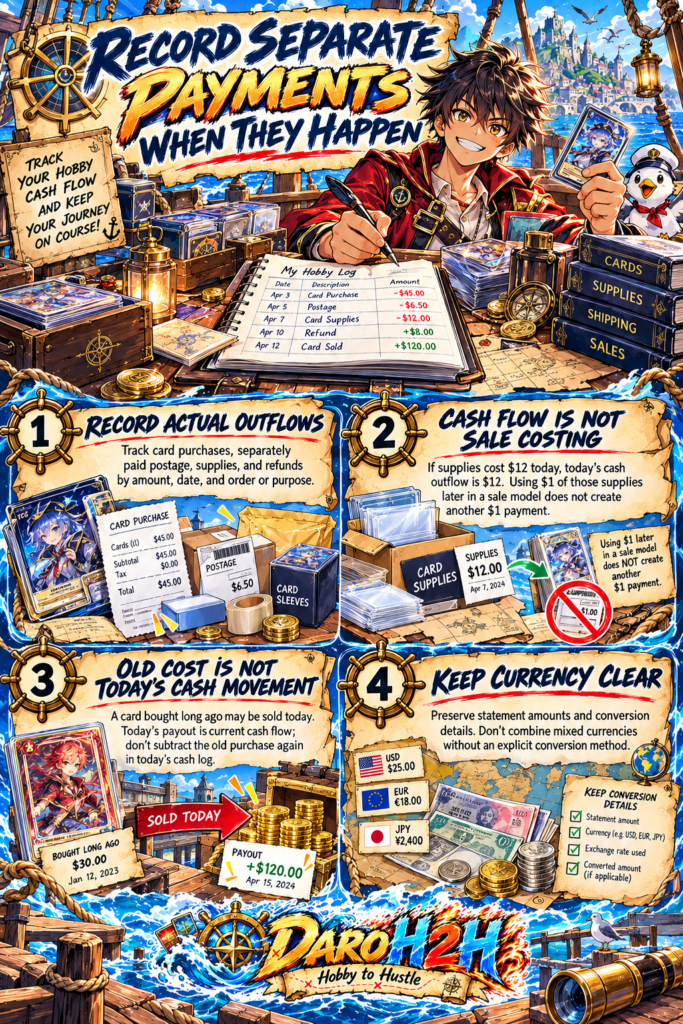
Card purchases, separately paid postage, supplies and refunds you pay can create actual outflows. Record the amount and date of the movement, and connect it to the relevant order or purpose.
Supplies are an easy place to mix cash flow with per-sale costing. If you pay $12 for a pack of supplies today, today’s cash outflow is $12. You might later allocate $1 of supplies to a particular shipment in its sale-cost calculation, but consuming that $1 doesn’t create another $1 payment from the account.
The same principle applies to an old card you sell now. Its acquisition payment may have happened months or years ago. Today’s payout is current cash movement; subtracting the old purchase again in today’s cash log would confuse transaction gain with current-period cash flow.
Keep currency clear. If an account receives a converted amount, preserve the actual statement and conversion details rather than inventing an exchange rate that makes your spreadsheet tidy. A mixed-currency list cannot be added meaningfully without an explicit conversion method.
Handle refunds as new events linked to the old order
If a refund actually reaches the account, record the inflow and link it to the original purchase. If you pay a refund, record the outflow. Don’t delete the earlier transaction and lose the history of what happened.
A refund can be announced before it settles. Until money moves, keep it as pending information rather than an arrived inflow. Likewise, a marketplace adjustment withheld from a future net payout should be understood through that statement, not automatically entered as a separate bank payment too.
The Hobby Budget and Cashflow Log treats refunds received as reducing budget usage and refunds paid as increasing it. That is a budgeting convention for this tool, not a tax ruling. Use clear categories so a refund doesn’t get mistaken for a brand-new card sale.
Your spending limit is a separate decision
Choosing to make $100 of household money available for cards next month is a budget choice, not sales revenue. The example amount is arbitrary; use a limit that fits your own circumstances and obligations.
Sale receipts also don’t automatically increase the chosen spending limit in this log. You may decide to put some proceeds back into the hobby, save them or use them elsewhere. Make that decision explicitly rather than letting a sale silently authorize another purchase.
That separation is useful when a good selling month makes it tempting to spend more. A payout can improve the tracked balance while your planned spending limit stays unchanged. The two numbers answer different questions: how much money moved, and how much you chose to spend.
Unsold collection estimates belong outside both cash receipts and available bank money. A card’s apparent market value might be interesting, but it hasn’t paid for this month’s postage or the next binder.
Check the period without inventing missing history
For a defined tracked balance, a basic reconciliation is the opening balance plus recorded inflows minus recorded outflows. Transfers and the scope of the account need to be handled consistently for that comparison to make sense.
If you don’t know the opening balance, don’t enter zero merely to obtain a closing number. You can still track known movements for the period while leaving the full balance unavailable. Unknown rows should keep totals visibly partial rather than disappearing into a complete-looking answer.
Review the log against statements periodically. Look for duplicated payouts, missing supply payments, refunds recorded in the wrong direction and transfers mislabeled as sales. Fix a supported error when you find it; keep a note on anything unresolved.
Quick questions
Can I track cash flow when I don’t know what an old card cost?
Yes. Today’s payout can be recorded even when acquisition history is unknown. A gain or loss calculation needs additional information; the cash movement does not.
Should I record a sale when the buyer pays or when the payout arrives?
For a log following your receiving bank account, record the money when it arrives there. Keep the sale and pending payout in their own transaction records. If you track a different account boundary, define that consistently.
Is a positive cash-flow month proof that the hobby made a profit?
No. Purchases and sales may happen in different periods, and the log doesn’t establish acquisition cost, business expenses or taxable income. It shows the money movement within its stated scope.
Reconcile one payout first
Take one completed payout and match it to the platform statement. Record the money that arrived, identify withheld charges and check for costs paid separately. Once that one example is clear, repeat the same method instead of rebuilding the rules for every order.