A card sells for $40, but the payout isn’t $40. You paid for shipping, used some packing supplies and bought the card earlier. So how much did you actually make?
The answer depends on which question you’re asking. Sale amount, net proceeds, recorded gain or loss, and cash flow measure different things. Giving each number a clear name is more useful than calling all of them “profit” and wondering why your records don’t agree.
This is a reference for personal recordkeeping and the limited Daro H2H calculator model. It does not calculate taxable income, determine tax basis or replace business accounting.
The sale amount describes the transaction
The item sale amount is the amount assigned to the card or lot. Buyer-paid shipping can be a separate charge. Marketplace-collected tax and other amounts may also appear in the buyer’s checkout total, but you should not automatically count every checkout field as money belonging to you.
When using a label such as gross receipts, write down its scope. In the simple sale model here, start with the item amount plus buyer-paid shipping retained by the seller, before selling and fulfillment costs. A platform’s tax-reporting gross amount may use a different definition, so keep its actual statement rather than forcing it into your personal label.
The IRS Form 1099-K FAQs explain that the reported gross payment amount is not adjusted for items such as fees and refunds. It isn’t a ready-made profit number. Use the underlying records to understand why it differs from the money you received.
Net sale proceeds show what remains before acquisition cost
For this site’s simple transaction model, net sale proceeds are the item amount plus retained buyer-paid shipping, minus selling/payment fees, seller-paid outbound shipping, packaging consumed and other sale-specific costs.
Marketplace-collected and remitted tax stays outside those proceeds. It can still matter if a fee is calculated on a base that includes tax. That is a fee-model issue, not a reason to add the tax to your earnings.
Proceeds tell you what the sale produced after the entered selling costs. They do not yet answer whether you recovered what you originally spent acquiring the card. They may also differ from the platform payout when some costs are paid elsewhere or several orders share a payout.
Recorded gain or loss adds the acquisition amount
If a supported acquisition amount is recorded for that item or lot, subtract it from net sale proceeds. The result is a gain or loss under those entered records and cost assumptions.
That wording matters. A personal allocation from a larger lot may need review. A gift, inheritance or trade may have facts your simple ledger doesn’t resolve. Business expenses and tax rules can require different treatment. Don’t rename the result taxable gain or business profit just because the subtraction was correct.
If acquisition history is unknown, the recorded gain or loss is unknown. You can still calculate proceeds from known sale data. Replacing the missing acquisition amount with zero would make the output look complete while answering a different question.
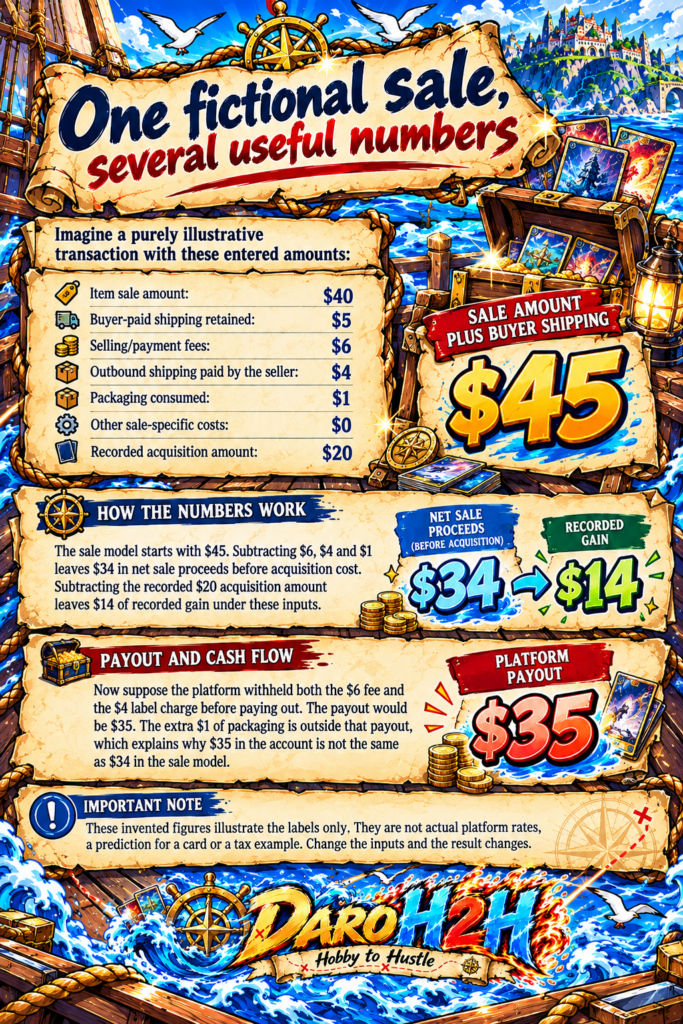
One fictional sale, several useful numbers
Imagine a purely illustrative transaction with these entered amounts:
- Item sale amount: $40
- Buyer-paid shipping retained: $5
- Selling/payment fees: $6
- Outbound shipping paid by the seller: $4
- Packaging consumed: $1
- Other sale-specific costs: $0
- Recorded acquisition amount: $20
The sale model starts with $45. Subtracting $6, $4 and $1 leaves $34 in net sale proceeds before acquisition cost. Subtracting the recorded $20 acquisition amount leaves $14 of recorded gain under these inputs.
Now suppose the platform withheld both the $6 fee and the $4 label charge before paying out. The payout would be $35. The extra $1 of packaging is outside that payout, which explains why $35 in the account is not the same as $34 in the sale model.
These invented figures illustrate the labels only. They are not actual platform rates, a prediction for a card or a tax example. Change the inputs and the result changes.
Cash flow follows money crossing your chosen boundary
Choose the account or pocket you’re tracking, then record money when it actually enters or leaves that scope. A net marketplace payout is an inflow. A separately paid purchase, postage charge or supply order is an outflow. Timing matters.
In the example above, entering the $35 net payout and then subtracting the already-withheld $6 fee and $4 label again would count the same costs twice. They are useful transaction details, but they didn’t separately leave the tracked bank account after that net payout.
Packaging shows another difference. The $1 consumed in this sale might come from a supply pack you paid for last month. The sale model can allocate $1 to the order, while today’s cash log has no new packaging payment. Record the actual supply purchase when it happened; don’t create a second cash outflow each time you use part of it.
Unsold estimates belong somewhere else
A card you still own may have a price estimate, but it hasn’t created a sale receipt or bank deposit. Keep collection estimates separate from cash-flow totals and clearly label their observation date and uncertainty.
Likewise, choosing a hobby budget doesn’t create sales revenue. If you set aside household money for cards, record that budget decision or transfer in the appropriate place. It is not evidence that your collection earned that amount.
Quick questions
Which number tells me what I can spend right now?
Actual available money in the account or pocket you use is the starting point, alongside your budget and other obligations. A planned sale, pending payout or estimated card value isn’t automatically available cash.
Why is my payout different from my proceeds calculation?
The payout may combine orders, withhold some costs, include adjustments or arrive in a different period. Your proceeds calculation may include costs paid separately. Reconcile the statement line by line rather than forcing the numbers to match.
Can the calculator tell me my tax bill?
No. Its outputs describe entered transaction amounts and a limited cost model. Taxable income, basis, deductions and filing obligations require the applicable rules and your actual circumstances.
Label the number before using it
When you write down an amount, add what it represents: item price, net payout, modeled proceeds or recorded gain. That tiny habit prevents a lot of confusion when you price the next card, check the hobby budget or prepare records for a professional.