A hobby-money review doesn’t need to feel like running a small company. You’re trying to answer a practical question: after what actually happened this month, what spending limit makes sense next month?
That means separating money that moved from cards you still own, checking what fees were already deducted, and keeping unresolved records visible. A few completed sales can help fund the hobby, but they don’t automatically mean you made a profit or that the next purchase is affordable.
Set aside a short, calm session with the records you have. The point is to make the next decision clearer, not to judge whether every card purchase was mathematically impressive.
Choose the period and what the review covers
Pick a start and end date, usually a calendar month, and use the same boundaries for the records you compare. A payment made this month, a card purchased last month, and a pending payout expected next month shouldn’t quietly slide into whichever column makes the total look better.
For a simple cash review, focus on amounts that actually came in or went out during the period. Keep pending orders, expected refunds, and platform balances that haven’t reached the account you’re tracking in clearly labeled separate notes. If you use a different convention, document it and apply it consistently.
Define the hobby costs you’re including. Cards, sleeves, storage, postage, show admission, and grading can all be part of the picture if they fall within your chosen scope. A budget that covers only card prices can still be useful, but label that boundary so it doesn’t pretend to describe the whole hobby.
Gather actual amounts before interpreting them
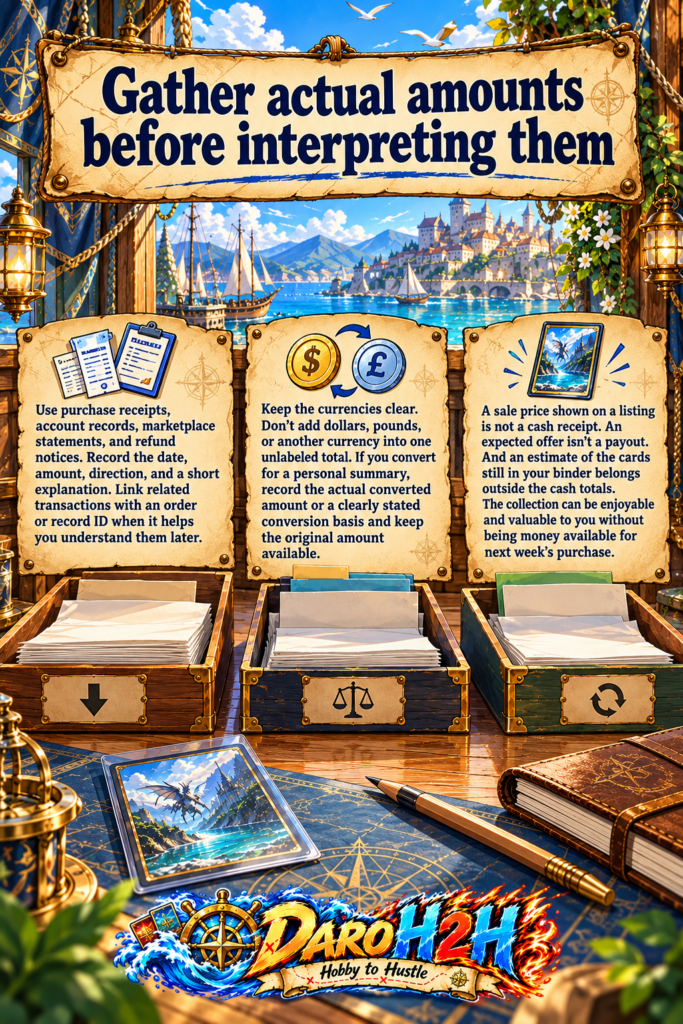
Use purchase receipts, account records, marketplace statements, and refund notices. Record the date, amount, direction, and a short explanation. Link related transactions with an order or record ID when it helps you understand them later.
Keep the currencies clear. Don’t add dollars, pounds, or another currency into one unlabeled total. If you convert for a personal summary, record the actual converted amount or a clearly stated conversion basis and keep the original amount available.
A sale price shown on a listing is not a cash receipt. An expected offer isn’t a payout. And an estimate of the cards still in your binder belongs outside the cash totals. The collection can be enjoyable and valuable to you without being money available for next week’s purchase.
Catch the common double-counting trap
A platform may send a payout after withholding fees, labels, or other deductions. If you enter that net payout as cash received and then subtract the same deductions again, your summary understates the cash that remained.
Read the statement rather than guessing. One order might have a label deducted from its proceeds, while another shipping cost was paid separately. The correct cash entries depend on what actually happened, not what usually happens on that platform.
You can keep a detailed transaction view showing gross amounts and deductions alongside a cash view showing the net payout. Just don’t add both versions to the same cash total. Similarly, moving money between your own accounts shouldn’t appear as a fresh card sale merely because it arrived in the account you use for the hobby.
Keep refunds connected to the original purchase
A refund is money coming back, but its meaning depends on the transaction. It might reverse a purchase from this month or one from an earlier period. Keep the original purchase and the refund identifiable rather than deleting the purchase as though it never happened.
For the cash review, a refund received this month belongs in this month’s inflows under the chosen cash basis. For your spending-limit review, decide how refunds affect the budget and follow that rule consistently. Don’t change the convention halfway through a month just to create room for another card.
If a refund is promised but hasn’t arrived, mark it pending. You can investigate it without treating the expected amount as money already available.
Work through one complete month
Here’s a hypothetical example using dollars and a simple cash basis. A collector chose a $200 monthly hobby limit. During the month, they paid $145 for cards, $25 for supplies, and $10 in separately paid shipping. Actual outflows were $180.
They also received $45 in net seller payouts and a $15 refund from an earlier purchase. Actual inflows were $60. The cash movement for the period was therefore $60 in minus $180 out, or $120 out overall.
For this example, the collector counts all $180 of spending against the $200 limit and doesn’t automatically add payouts or the older refund back into the current allowance. That leaves $20 under the chosen spending rule. The $120 net cash outflow answers a different question from the $180 spent. Neither number, by itself, is taxable profit.
Suppose the collector paid for one sold card years ago and no longer knows its acquisition cost. They can still accurately record today’s $45 net payout. The missing cost limits any gain-or-loss conclusion; it does not make the known cash receipt disappear.
Now suppose one shipping payment is missing from the records. That affects the cash total itself. Until the amount is recovered, the month should be labeled incomplete rather than presented as an exact result. These two kinds of missing information have different consequences.
Compare the result with what you wanted from the month
Look beyond whether you were under the ceiling. Did the purchases move a collection you care about forward? Did several small shipping charges surprise you? Did buying supplies solve a real storage problem, or did you spend more time shopping for storage than enjoying the cards?
You aren’t required to prove that every purchase will retain value. An affordable card bought because you like the artwork can be a satisfying hobby expense. What matters for this review is whether the spending fit your life and whether you’d make similar choices again.
If you exceeded the limit, identify the reason without rewriting the records. Maybe a purchase was larger than planned, a fee was overlooked, or several “small” pickups accumulated. Knowing which happened gives you a better next rule than simply deciding to try harder.
A month with no sales is still a normal hobby month. You can choose a spending boundary based on available discretionary money without requiring the collection to pay for itself.
Choose next month’s limit deliberately
You have three broad options: keep the current limit, adjust it, or pause discretionary purchases. The right choice depends on your wider finances and priorities, not just this month’s card totals.
The Daro budget approach is deliberately conservative about sales: incoming proceeds don’t automatically enlarge the next spending limit. If you want to allocate some of that money to a new purchase, make that a fresh decision after the records and household priorities are clear.
You might keep the same limit but change how you use it, such as saving toward one wanted card rather than making several unrelated purchases. You might reduce it while a return or missing record is unresolved. Or you might pause shopping and spend a month organizing or enjoying what you already own.
Write down the amount, period, included costs, and any chosen refund treatment. A simple rule you can recognize next month is more useful than a complicated budget you immediately stop updating.
Keep tax decisions out of the spending calculation
The U.S. IRS describes Form 1099-K as a report of payments that should be used with other records when determining tax reporting. See its current explanation. The form, a marketplace payout, a cash-flow total, and a personal spending allowance answer different questions.
If sales, trades, missing acquisition records, or the pattern of activity create a tax or classification question, take the records to a qualified professional. This guide is a personal hobby review; it doesn’t determine tax liability or provide a filing method.
Finish by saving the updated record and a backup, listing any amounts still unresolved, and writing the next month’s decision. Then close the money review. Its job is to make room for enjoying the collection with fewer unpleasant surprises.
Quick questions
Do sales automatically increase my card budget?
Only if you deliberately choose that rule or make a new allocation. This guide’s conservative approach keeps the spending decision separate from incoming proceeds.
What if my cards went up in estimated value?
Keep that estimate outside cash flow. Unsold cards haven’t created a cash receipt, and an estimate isn’t a guaranteed future sale.
Can I review the month with incomplete records?
Yes, but label what is incomplete and how it affects the result. Missing cash amounts make cash totals partial. Missing old acquisition costs limit different calculations.
Is a month with net money coming in a profitable month?
Not necessarily. Net cash movement does not, by itself, establish profit, return, or taxable income. Keep the underlying transactions and cost history available.